

The envelope looks like a form letter, and it reads like a closed door. You've been with the same employer for nine years. You pay your bills on time. You've saved for a down payment. Then the adverse-action notice arrives with a reason printed next to a phrase you didn't expect, and the assumption sets in that homeownership just moved out of reach.
It hasn't. In most files, a mortgage denial traces to one or more specific, identifiable issues, and identifiable issues can be worked on. Sometimes the file contains information that's wrong. Sometimes the debt load is too heavy for the loan amount you wanted. Sometimes the lender never received the document that would have answered the question. The notice is a diagnosis, not a sentence.
What follows are eight of the most common mortgage denial reasons, written the way an underwriter reviews them. Each one pairs the review lens with a realistic example and the next step that fits the cause: a documented dispute when the information is wrong, statement-date planning when a balance is too high relative to a limit, a timing strategy when a major event needs to age, or better paperwork when nobody did anything wrong at all.
Requirements differ by loan program (FHA, VA, conventional, USDA) and by individual lender, so confirm specifics with your loan officer. Outcomes depend on your file, your documentation, and what you do next.
Table of Contents
- 1. Low Credit Score or Limited Credit History
- 2. High Debt-to-Income Ratio
- 3. Recent Late Payments on Credit Accounts
- 4. Collections and Charge-Offs
- 5. High Credit Card Utilization
- 6. Credit Report Errors and Inaccurate Information
- 7. Insufficient or Unverifiable Income, Employment, and Asset Documentation
- 8. Recent Major Credit Events and New Credit Activity
- 8 Mortgage Denial Reasons at a Glance
- Reading Your Denial Letter and Building a Lender-Ready File
1. Low Credit Score or Limited Credit History
A credit score is a summary, not a verdict. Lenders use a three-digit number built from the information in your credit report, and the CFPB's mortgage key terms explain that consumers have several scores because scoring models differ, so the number a mortgage lender pulls may not match the one in a free phone app.
Each loan program sets its own floor. The CFPB notes that FHA loans permit lower credit scores and down payments as low as 3.5 percent of the total loan amount, which in practice often means a 580 score paired with that down payment, and some lenders go lower when the down payment is larger. Conventional loans commonly look for scores around 620. VA and USDA carry their own standards, and many individual lenders stack stricter internal rules, known as overlays, on top of program minimums.
Reading your own reports before a lender does is the least expensive step available.
When the score isn't the problem, the file depth is
Say you have a 610 score and 14 months of history on two cards. An FHA lender and a conventional lender may review that same file very differently, because each program and each lender applies its own rules. A file with only two recently opened accounts can also be too thin to score or too thin to show a pattern, and an underwriter can't approve what can't be measured.
- Ask which scoring model and minimum apply to your program before you apply, not after a denial.
- Review all three bureau reports so you know what each one says about balances, limits, and dates.
- Keep older accounts open when it costs you nothing, since account age feeds several models.
- Pause new applications for store cards or auto financing in the months before you apply.
If your file is short on history rather than damaged, renters building credit for homeownership covers how to add depth before anyone pulls a mortgage inquiry. When the issue really is the score, the fix is rarely a mystery product. It's utilization, payment history, and time.
2. High Debt-to-Income Ratio
Debt-to-income ratio is simple arithmetic with a lot of weight behind it. Divide total monthly debt payments by gross monthly income, meaning income before taxes. That percentage is what an underwriter uses to judge whether the proposed housing payment still fits beside everything else you owe.
The ratio has two forms, and mixing them up is a common reason a file looks fine at home and fails in underwriting. The front-end ratio counts only housing costs: principal, interest, property taxes, insurance, and any association dues. The back-end ratio adds the rest, including auto loans, student loans, minimum card payments, personal loans, and court-ordered support. Lenders usually underwrite the back-end figure, the one that includes the new mortgage. Housing alone can look comfortable while the full stack of required payments does not.
Picture the paycheck as a suitcase. Each required monthly payment is an item that already has to fit. The mortgage is the last item the underwriter tries to pack. A strong credit file does not make the suitcase larger.
Why DTI has become the deciding factor
Higher mortgage rates raise the proposed payment, which lifts the ratio even when income and the credit record have not changed. Analysts at the Federal Reserve Bank of St. Louis, reviewing more than 30 million home-purchase applications, found that DTI was the primary rejection reason in 29% of denials in 2018 and 35% in 2024, making it the largest single denial category that year.
Qualified-mortgage debt-to-income limits have changed over time. Each loan program and each lender sets its own threshold, so confirm the current limit for your loan type before treating any single percentage as a rule. A ratio just over one program's line is not an automatic denial everywhere, and a ratio under that line is not an automatic approval. Income documents, reserves, and the rest of the file still get read.
A household with $6,000 in gross monthly income and $2,700 in existing debt payments sits at 45 percent before the mortgage payment is added. The credit file can be clean. The arithmetic is still the problem.
What the underwriter examines is the required monthly payment on each debt, not which balance feels largest. A small balance with a high payment can move the ratio more than a large card balance with a small minimum. Bring statements that show the payment due, the remaining term, and whether a loan is about to end. Ask which debts this lender counts. Student loans, lease payments, and support obligations are treated differently across programs.
A dispute fits only when a listed debt is not yours, is already paid off, or shows the wrong required payment, and you can document that with statements or payoff records. An accurate auto loan or student loan stays on the file. For those accounts, the useful moves are paying off a large required payment, timing an application after a loan is scheduled to end, or lowering the payment the bureau will report. Disputing an accurate obligation will not create room in the ratio.
Practical rule: Run the ratio twice, once with today's debts and once with the proposed housing payment included. The second number is the one being underwritten.
Avoid new financing before closing. A vehicle loan taken mid-process can change the ratio overnight. Target the payment, not just the balance. Eliminating a large required monthly payment moves the ratio further than shaving a card balance that has a small minimum.
Ways to reduce your debt-to-income ratio walks through that sequencing in more detail.
3. Recent Late Payments on Credit Accounts
Two weeks after a calm preapproval conversation, the file comes back with a credit-history denial. The mortgage itself was current. A card payment posted 30 days late four months earlier, and that recent mark is what the underwriter stopped on.
Payment history sits near the center of most scoring models. Underwriters read it the way an editor reads a draft: the newest pages get the closest look. Lenders typically review at least the last 12 to 24 months. One isolated slip and a run of lates are different files.
An Urban Institute analysis of 1,689,679 denied forward-mortgage applications found credit history, the category where payment history lives, listed as a denial reason in about 30.6% of those applications, and 16.1% of denials cited two reasons at once. A letter can name more than one reason. A late payment may share that letter with something else, or it may be the line that stops the file on its own.
Dispute or rebuild, deciding which one fits
The underwriter's lens is the date, how late the account went (30, 60, or 90 days), and whether payments have stayed current since. Your next step depends on whether that date is accurate.
A single 30-day late on a card four months before applying is often survivable when later payments are clean. Plan on a short letter of explanation and several months of on-time history you can show.
A late that never happened is a records problem. If the auto loan shows 60 days past due and the bank statement shows the payment cleared on time, dispute the item with the bureau and the furnisher. Match the reporting date to the payment date, then attach statements, confirmation numbers, and the account timeline. An accurate late is not fixed by another dispute. It needs a payment calendar, proof of each payment after the miss, and time on the report before you reapply.
The 120-day foreclosure rule explains how far behind a mortgage can fall before formal action begins. A housing late is a heavier mark than a card late, and the timeline matters because missed payments stack.
A late payment you can prove was on time is a documentation problem. One that genuinely happened is a history problem, and history gets rebuilt with time.
- Automate at least the minimum. A scheduled payment removes the most common cause of an avoidable 30-day late.
- Keep confirmations. Screenshots, statements, and correspondence are the evidence if a date is wrong.
- Ask how recent lates are weighted under your specific program before you apply.
Late payment advice for first-time homebuyers covers the letters and timelines in more detail.
4. Collections and Charge-Offs
Two words get used interchangeably, and they shouldn't be. A collection account appears when an unpaid debt is transferred to a collection agency or to a creditor's internal collection department. A charge-off happens when the creditor decides the debt is unlikely to be collected and writes it off for accounting purposes, usually after roughly six months of nonpayment. The balance is still owed, and it still reports.
Mortgage lenders generally want both addressed, though how they want them handled depends on the loan type, the amount, and the lender's own guidelines. Some programs require a collection to be paid or settled before closing. Others only require it to be documented. Ask before you send money, because how a debt is paid can matter as much as whether it is.
What a lender expects to see
Dispute only where accuracy is the question: a debt that isn't yours, a wrong amount, duplicate reporting, or information the collector can't verify. A legitimate unpaid debt isn't a dispute candidate. It's a payment or negotiation conversation.
- Request written validation of the debt from the collector as soon as the notice arrives.
- Get every agreement in writing and keep proof of each payment made.
- Confirm the lender's rule first, since paying a collection doesn't automatically remove it from your report.
- Talk to a qualified professional about very old debts before sending money, because payment activity can have legal consequences in some situations.
Medical collections deserve their own note. Certain scoring models disregard paid medical collections and give less weight to smaller unpaid balances, but mortgage lender rules vary and should be confirmed directly rather than assumed.
Clearing collections before applying explains how a paid account reads to an underwriter compared with an unpaid one.
5. High Credit Card Utilization
Picture a card with a $5,000 limit and a $4,500 balance. That's 90 percent utilization on a single account, and it makes an underwriter's job harder no matter how clean your payment record is.
Credit utilization is the share of available revolving credit currently in use. Scoring models look at each card individually and at the total across all cards, so spreading balances around doesn't help if the combined figure stays high relative to combined limits. A common guideline is to keep utilization below 30 percent, and many buyers aim lower, but no single number guarantees a particular outcome.
Statement dates decide what gets reported
Utilization is usually reported once per billing cycle. A payment made today may not appear on a report for several weeks, which is why timing matters as much as the amount.
Timing note: A balance paid down before the statement closes reports lower. The same payment made a week later reports high for another full cycle.
- Pay before the statement closing date when you want a lower balance reflected.
- Reduce steadily instead of relying on one large payment you can't repeat.
- Think before requesting a limit increase, since some requests trigger a hard inquiry.
- Track installment obligations, including buy now, pay later plans from providers like Affirm, Klarna, Afterpay, and Sezzle, and disclose them accurately when you apply.
High utilization also signals strain to a reviewer who is scanning for risk. That's why credit utilization and mortgage approval are so tightly connected, and why a balance plan built around statement dates often does more for a file than another dispute.
6. Credit Report Errors and Inaccurate Information
Before you accept that your history is the problem, confirm the history is yours. Errors are common, and they're easy to miss because many borrowers never read their reports line by line.
A denial based even partly on information in a consumer report generally triggers an adverse-action notice under the Fair Credit Reporting Act. The CFPB's guidance on consumer reporting companies explains that the notice must identify the agency that supplied the information, along with its name, address, and telephone number. That's your starting point for checking whether the file the lender saw contained an inaccurate balance, a wrong date, a duplicate debt, or an account opened by someone else.
The dispute process, step by step
Timelines are defined. Furnishers such as lenders and collection agencies generally must investigate and respond within 30 days, and the CFPB's answer on disputing a credit report error notes that consumer-reporting agencies generally respond within 30 to 45 days, depending on the circumstances and whether additional information is submitted.
- Pull all three reports through the official free reporting service authorized under federal law.
- Identify the exact field being challenged: account number, balance, date, or payment status.
- Attach evidence, such as statements, confirmation numbers, or an identity theft report.
- Track delivery and response dates so you know when an investigation is overdue.
An account listed twice, once by the original creditor and once by a collection agency, can overstate the negative history on a file. So can an account from a lender you've never used. Both are accuracy questions, and accuracy questions have a process. Disputes correct facts. They don't erase accurate history, and a vague disagreement with a negative but accurate account isn't the same as a factual dispute.
7. Insufficient or Unverifiable Income, Employment, and Asset Documentation
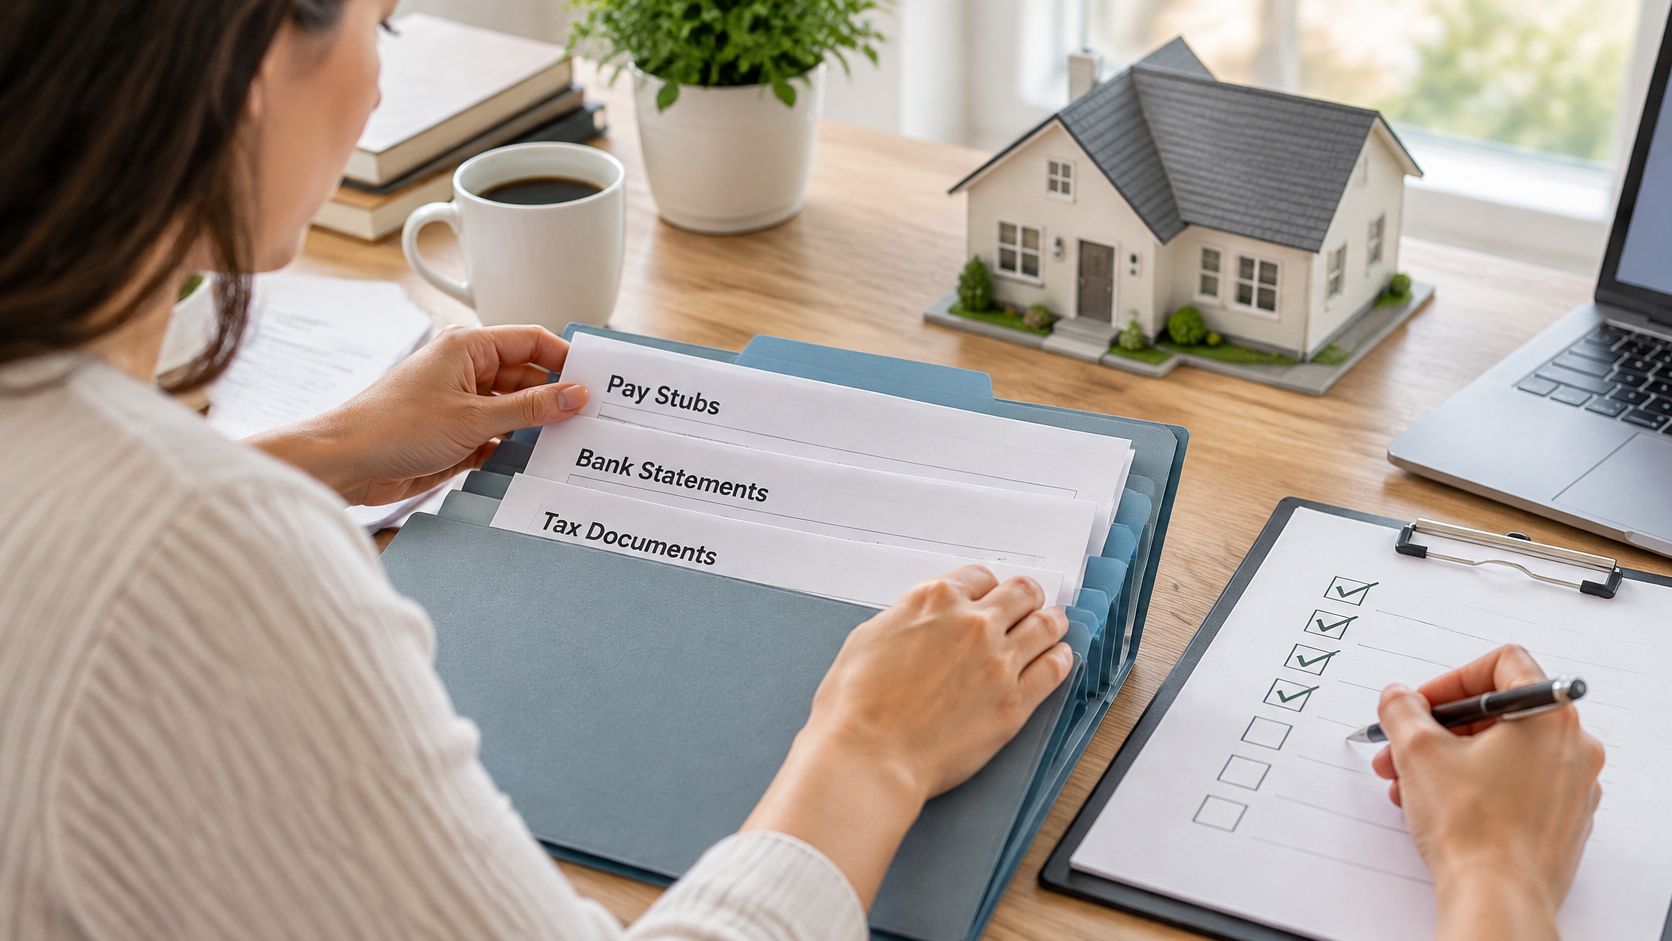
Credit is only half the file. An underwriter also has to verify that your income is stable and sufficient, that your employment history holds up, that you have funds for the down payment and closing costs, and in some cases that reserves will remain after closing.
A documentation denial is often the most preventable kind, but only when the records are organized before someone asks for them.
What underwriters actually verify
Expect requests for recent pay stubs, W-2 forms, tax returns, bank statements, and a written or verbal employment verification. Self-employed borrowers often need two years of returns, and qualifying income may be averaged across years or reduced if it has declined. A Bookkeeping and Accounting of Florida's guide is a useful reference for organizing business financial statements before a review.
- Gather two years of returns or W-2s, recent pay stubs, and recent bank statements early.
- Document the source of every large deposit, whether it's a property sale, a gift, or a transfer between accounts.
- Don't change jobs or move large sums mid-process without telling your loan officer.
- Write a brief, factual letter of explanation for any employment gap or irregularity.
Say your tax returns show lower self-employment income in the most recent year. The lender may need a clear explanation and additional documentation before it can settle on a qualifying figure. Say you had a three-month gap after a layoff. A short written explanation plus proof of your new income source usually resolves the question. The file stops when the paperwork stops.
8. Recent Major Credit Events and New Credit Activity
Some denials are about timing. Bankruptcy, foreclosure, short sale, and repossession often come with mandatory waiting periods, and the clock depends on the program, the event, and whether extenuating circumstances apply.
Waiting periods differ by loan program
As general ranges, FHA guidelines often allow a Chapter 7 discharge after about two years and a foreclosure after about three years. VA timing is often similar for bankruptcy. Conventional guidelines commonly run longer, around four years after a Chapter 7 discharge and roughly seven years after a foreclosure. Chapter 13 has its own rules and can allow earlier approval in some cases.
A borrower whose Chapter 7 was discharged about two years ago may be evaluated differently under FHA or VA than under conventional guidelines, even with identical credit behavior since the discharge. That's a program question, not a character question, and a lender can answer it in one conversation.
Nothing about a mortgage application pauses your financial life, but the file is being read in real time. A financed purchase between pre-approval and closing can send the whole file back to underwriting.
New credit activity raises a separate concern. Multiple hard inquiries, several newly opened accounts, and recent financing all suggest increasing obligations, and buy now, pay later plans that report to the bureaus count too.
- Ask for the specific waiting period that applies to your event and program.
- Keep discharge papers, foreclosure records, and repossession documents on hand.
- Avoid opening accounts in the months before applying.
- Disclose every obligation accurately, including short-term financing.
A borrower who opened three retail accounts in two months before applying may be asked to explain the purpose of that new credit. Have the answer ready, in writing.
8 Mortgage Denial Reasons at a Glance
| Denial Reason | What Underwriters Review | Key Factor or Guideline | Typical Next Step |
|---|---|---|---|
| Low Credit Score or Limited Credit History | Credit scores, payment patterns, and length of credit history | Minimums vary by loan program and lender; thin files may lack enough history | Confirm the lender's score requirements and review all three credit reports |
| High Debt-to-Income Ratio | Gross income, housing costs, and total monthly debt payments | Program limits vary; automated underwriting and compensating factors may affect the result | Review included debts and consider reducing monthly obligations |
| Recent Late Payments on Credit Accounts | Payment history, often covering the past 12 to 24 months | Recent and repeated late payments can signal ongoing risk | Build a record of on-time payments and dispute any reporting errors |
| Collections and Charge-Offs | Unpaid debts, account status, balances, and any payment arrangements | Treatment varies by loan type and lender; paid status may not remove an account | Confirm lender requirements and document any payment arrangement or accuracy dispute |
| High Credit Card Utilization | Reported balances compared with individual and total credit limits | Lower utilization is generally viewed more favorably; balances may update after a billing cycle | Reduce balances and consider payment timing before the statement closes |
| Credit Report Errors and Inaccurate Information | Account ownership, balances, payment statuses, duplicate entries, and outdated items | Inaccurate or unverifiable information may be disputed under the Fair Credit Reporting Act | Review all three reports and submit documented disputes well before applying |
| Insufficient or Unverifiable Income, Employment, and Asset Documentation | Income, employment history, assets, reserves, and deposit sources | Self-employed income may require multiple years of tax returns; unexplained deposits need documentation | Gather financial records early and explain gaps or irregularities |
| Recent Major Credit Events and New Credit Activity | Bankruptcy, foreclosure, repossession, inquiries, and recently opened accounts | Waiting periods vary by event and loan program; new credit may raise concerns | Confirm the applicable waiting period, keep event records, and avoid new credit before applying |
Reading Your Denial Letter and Building a Lender-Ready File
The adverse-action notice in front of you lists reason codes, and those codes are the page the underwriter wrote. Read the primary reason first, then the secondary ones. If the notice names a credit report as the source, request the exact report the lender pulled and line it up against your own copies from all three bureaus. A mismatch in balance, status, or ownership is worth writing down the same day, with the page number and the date.
Match each reason to the response that fits it. A wrong balance, a duplicate collection, or a payment marked late when your records show it was on time calls for a documented dispute with the proof attached. A high utilization figure calls for statement-date and balance planning, not a dispute, because the balance is real and the bureau is reporting what the card issuer sent. An accurate collection, a charge-off, or a recent bankruptcy calls for payment strategy, timing, and rebuilding. A missing tax return or an unexplained deposit calls for paperwork.
Disputing an accurate item burns weeks that do not come back. Paying a balance down does not repair a file that still contains an error. The underwriter looks through one lens at a time: is this item wrong, or is it true and too heavy for this loan right now?
Does paying off a collection guarantee mortgage approval?
No. Paying a collection may satisfy one lender condition, but approval still depends on the full loan profile: income, debts, assets, credit history, down payment, and the property itself. Some lenders want the collection paid before closing. Others only want it documented. Confirm that rule before you send the payment, and keep the receipt with the account number and the date.
How soon can I reapply after a denial?
There is no universal waiting period. A documentation gap can be a matter of days once the missing pages are in the file. A credit or ratio problem needs enough time to change the number the underwriter cited, which often means several months of on-time payments and lower reported balances. Ask that lender what would have to change, and write the answer next to the reason code.
Can I be denied with good credit because of my debt-to-income ratio?
Yes. A strong score does not override a heavy debt load. Urban Institute data on mortgage denials shows debt-to-income was cited in 44.3% of denials among low- and moderate-income applicants compared with 23.1% among high-income applicants, which reflects how much the ratio depends on income rather than credit behavior alone.
Is credit repair legal, and what can it realistically do?
Yes, it is legal. The Fair Credit Reporting Act gives you the right to dispute inaccurate, incomplete, or unverifiable information, and both the furnisher and the reporting agency must investigate. It cannot remove accurate, current, or verifiable information. No company can guarantee a deletion, a score increase, an approval, or a timeframe, because results vary by consumer file and by how the bureau or creditor responds. An accurate negative account may need rebuilding, a payment plan, documentation, or time rather than another dispute.
Property and insurance conditions can stall a file that was otherwise on track. Avoid closing delays on manufactured homes shows how documentation on the home itself can affect timing.
Superior Credit Repair builds a next-step plan after a denial, before reapplying, or before a mortgage, rental, or auto application. Engagements use goal-based, pay-as-you-go plans with no setup fees and no long-term contracts, backed by more than 20 years of experience. Each account is reviewed separately.
If this information helped you better understand your credit report or your next steps, we would appreciate your honest feedback. You are welcome to share your experience with Superior Credit Repair on our Google Business Profile. https://share.google/ePRpFvtCXwCjiJwOK
When you request a credit analysis, bring your three current credit reports, photo identification, current address information, recent statements for any accounts you want reviewed, collection notices, payment confirmations, and the denial or adverse-action notice that prompted your search. Superior Credit Repair will read each reason code against the file, separate genuine reporting errors from accurate items that need a payment plan or more time, and lay out a step-by-step route back to a lender-ready credit profile. Visit Superior Credit Repair to start that review before you reapply.