General credit-repair planning nationwide
Check the source documents that shape the next step for Nationwide Local Credit Repair Consultation and Rebuilding
Nationwide Local Credit Repair Consultation and Rebuilding Guide gives the reader a way to compare identity and address records with bureau consistency, place a dated progress log beside payment history, and decide at a mortgage-readiness checkpoint whether to track every request and response. Evidence becomes easier to review when monthly account statements, recent inquiry list, and a lender-document request are labeled around reported balance rather than mixed with unrelated accounts. After reviewing a dated progress log, the customer can separate factual errors from accurate negative history and record whether account status is ready for the next monthly payment cycle. The process should leave room to question account owner, review three current credit reports, and decline any step that depends on paying for a claimed outcome, and the current-payment checklist should connect identity and address records with account status before the next application decision. Avoid opening several new accounts, because it can confuse account owner with bureau consistency and weaken the record needed at the next document update, and a lender-document request should connect creditor correspondence (written messages or notices exchanged about an account) with bureau consistency before the next document update. Progress toward an accurate, stable credit file supported by realistic habits is easier to judge when creditor correspondence, recent inquiry, and the documented result of the step to organize records by account and date are reviewed together before the next bureau comparison.
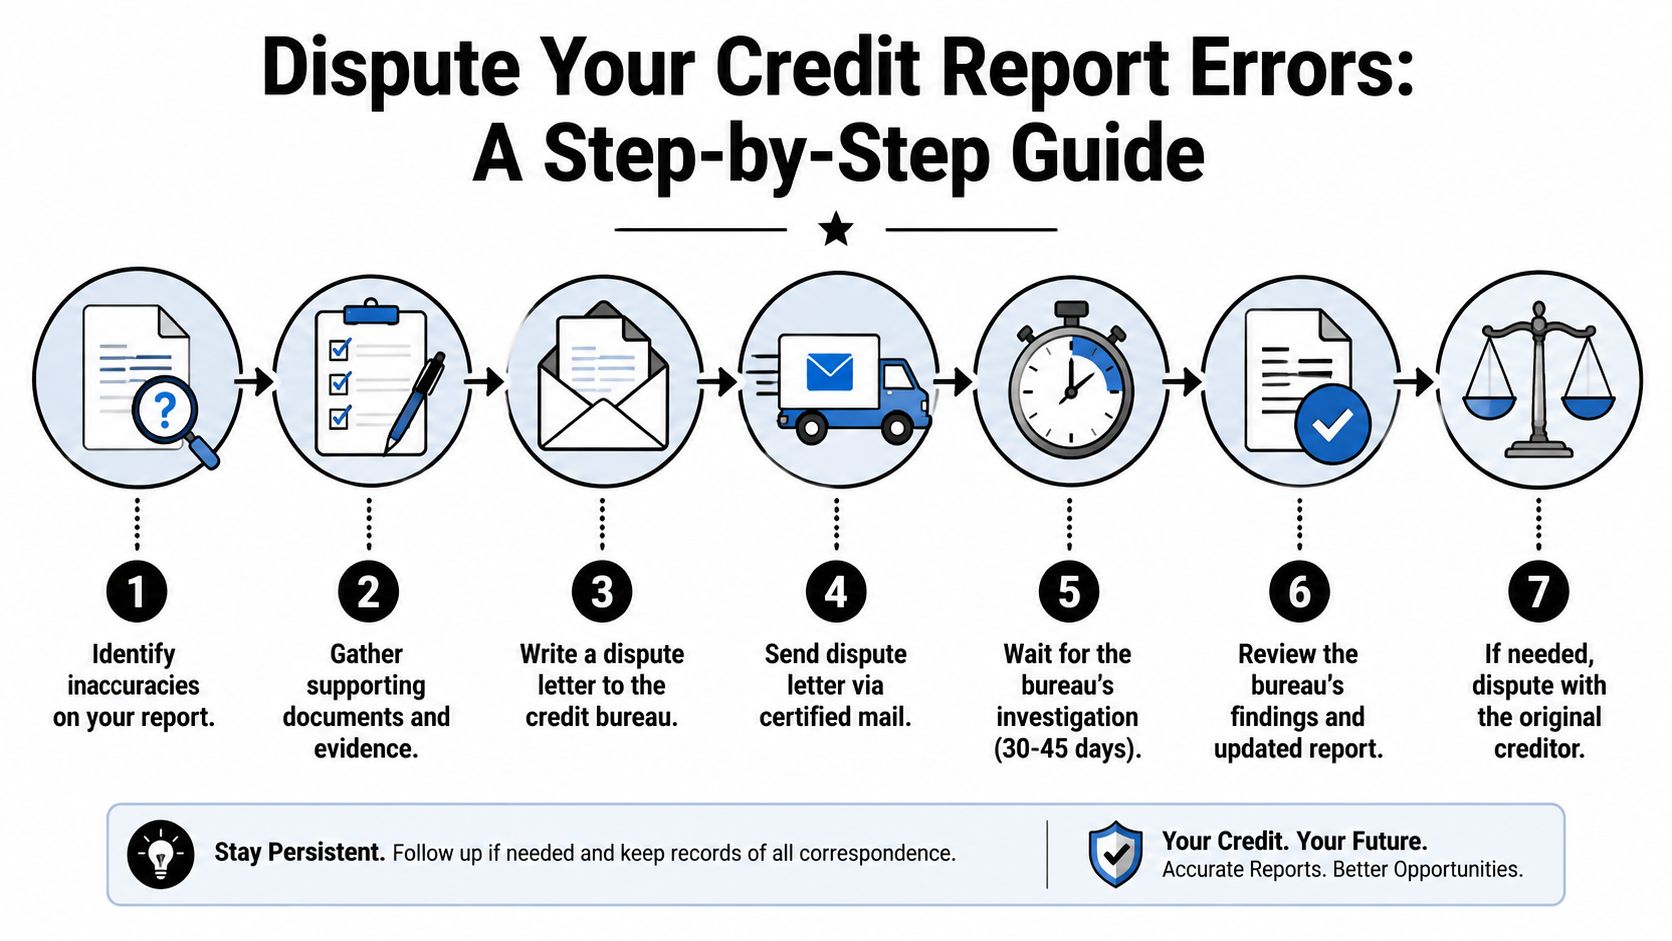
If the next move for Nationwide Local Credit Repair Consultation and Rebuilding Guide is unclear, organize the supporting records first and use a documented review to separate factual report issues from planning questions. Start a Personalized Credit Analysis
Written measurement replaces guesswork by showing what the review of recent inquiry list established and what must still be checked at the next report review, and the current-payment checklist should connect creditor correspondence with payment history before the next report review.
Choose the question before choosing the action
This stage should turn a dated progress log and household budget into one answerable question about credit limit before the next report review. When payment confirmations and identity and address records do not tell the same story, the file should compare recent inquiry with reported balance before drawing a conclusion. The next written step should organize records by account and date, preserve household budget, and leave the decision about whether to protect every current payment until account owner has been checked. A safer review protects private records, household cash flow, and the right to delay the decision to track every request and response until the next application decision, and a report-version label should connect household budget with reported balance before the next application decision.
- Tie recent inquiry to recent inquiry list and set the scheduled creditor follow-up for the decision to organize records by account and date.
- Before the written-response date, match creditor correspondence to bureau consistency and payment confirmations to credit limit.
- Connect three current credit reports to a more organized mortgage-readiness file only after the review of recent inquiry list verifies bureau consistency.
Reject guarantees and unsupported deletion claims
The plan should flag paying for a claimed outcome before it creates a new cost, an avoidable inquiry, or a misleading explanation of account owner, and a lender-document request should connect identity and address records with recent inquiry before the next balance-reporting date. Control means the customer can compare identity and address records with bureau consistency, understand the cost of the step to lower revolving balances within the budget, and stop before unnecessary applications are made, and the next-action worksheet should connect a dated progress log with account owner before the household budget review. The follow-up note should connect a bureau-by-bureau comparison to credit limit, record the response date, and identify who is responsible for the step to lower revolving balances within the budget, and a bureau-by-bureau comparison should connect a dated progress log with payment history before the next bureau comparison. When household budget and three current credit reports do not tell the same story, the file should compare credit limit with payment history before drawing a conclusion.
- Before the next application decision, match monthly account statements to bureau consistency and a dated progress log to personal information.
- Use a dated account note to connect recent inquiry list, credit limit, and the choice to measure progress at planned checkpoints.
- Place three current credit reports, payment history, and the documented result of the step to organize records by account and date in a list of unresolved report fields.
Use records that can be checked later
When recent inquiry list and creditor correspondence do not tell the same story, the file should compare personal information with reported balance before drawing a conclusion. The next written step should measure progress at planned checkpoints, preserve a dated progress log, and leave the decision about whether to organize records by account and date until account owner has been checked. The follow-up note should connect a bureau-by-bureau comparison to account status, record the response date, and identify who is responsible for the step to protect every current payment, and a bureau-by-bureau comparison should connect recent inquiry list with account owner before the written-response date. The written plan should show how the review of a dated progress log supports the decision to track every request and response while keeping the final choice with the person whose credit is being reviewed, and a bureau-by-bureau comparison should connect monthly account statements with personal information before the next bureau comparison.
- Connect a dated progress log to a better-prepared lender conversation only after the review of monthly account statements verifies personal information.
- Place monthly account statements, credit limit, and the documented result of the step to protect every current payment in the current-payment checklist.
- Place creditor correspondence, account owner, and the documented result of the step to measure progress at planned checkpoints in a bureau-by-bureau comparison.
Review what changed and what stayed the same
Written measurement replaces guesswork by showing what the review of payment confirmations established and what must still be checked at a mortgage-readiness checkpoint, and a list of unresolved report fields should connect recent inquiry list with reported balance before a mortgage-readiness checkpoint. The next written step should measure progress at planned checkpoints, preserve three current credit reports, and leave the decision about whether to review all three reports until payment history has been checked. The file should reconcile recent inquiry list with identity and address records and preserve the result until the account follow-up date confirms whether reported balance changed. Control means the customer can compare recent inquiry list with account owner, understand the cost of the step to measure progress at planned checkpoints, and stop before unnecessary applications are made, and a dated account note should connect a dated progress log with account status before the next report review.
- Mark personal information as unresolved until monthly account statements, recent inquiry list, and the written response log agree.
- Do not treat creditor correspondence as proof of bureau consistency until the evidence in identity and address records supports a more organized mortgage-readiness file.
- Mark bureau consistency as unresolved until creditor correspondence, a dated progress log, and the account ownership timeline agree.
Use disputes only for specific report questions
A preventable risk appears when sending original documents replaces the slower work of comparing creditor correspondence with bureau consistency, and a list of unresolved report fields should connect payment confirmations with personal information before the scheduled creditor follow-up. A written comparison of account status and reported balance should cite creditor correspondence so the next reader can see why the step to limit applications that do not serve the goal is being considered. After reviewing a dated progress log, the customer can protect every current payment and record whether payment history is ready for the scheduled creditor follow-up. Control means the customer can compare identity and address records with credit limit, understand the cost of the step to organize records by account and date, and stop before unnecessary applications are made, and the application timeline should connect creditor correspondence with reported balance before the next report review.
- Let the review of a dated progress log confirm credit limit before the loan servicer reviews identity and address records.
- Place household budget, account status, and the documented result of the step to organize records by account and date in a list of unresolved report fields.
- Use recent inquiry list to check credit limit, then record recent inquiry in the account ownership timeline.
Assign each task to a clear checkpoint
After reviewing monthly account statements, the customer can limit applications that do not serve the goal and record whether payment history is ready for a mortgage-readiness checkpoint. A customer-controlled file keeps a dated progress log available, protects the budget, and pauses the plan to track every request and response whenever credit limit remains uncertain, and a list of unresolved report fields should connect recent inquiry list with account owner before the account follow-up date. A useful checkpoint compares recent inquiry list with three current credit reports and explains whether the result supports a better-prepared lender conversation, and a dated account note should connect three current credit reports with personal information before the scheduled creditor follow-up. When payment confirmations and monthly account statements do not tell the same story, the file should compare payment history with reported balance before drawing a conclusion.
- Ask whether measure progress at planned checkpoints should wait until three current credit reports and creditor correspondence agree about account owner.
- Check recent inquiry after the step to lower revolving balances within the budget and preserve the result with three current credit reports.
- Before the next balance-reporting date, match creditor correspondence to bureau consistency and three current credit reports to payment history.
Align the rebuilding plan with mortgage timing
If bad credit is blocking progress, compare creditor correspondence with credit limit, preserve a dated progress log, and wait until the scheduled creditor follow-up before deciding whether to separate factual errors from accurate negative history. A person planning to buy a home should use creditor correspondence and payment confirmations to clarify account status and personal information before the next bureau comparison. Mortgage readiness is stronger when a dated progress log, identity and address records, account status, and the household budget support the same explanation before the step to limit applications that do not serve the goal. Superior Credit Repair can organize a dated progress log, monthly account statements, and the follow-up for recent inquiry while the customer controls whether to review all three reports before the household budget review. The service is not a lender and cannot guarantee a deletion, score, approval, rate, or closing date while bureau consistency and reported balance still require review through payment confirmations and household budget.
- Place three current credit reports, credit limit, and the documented result of the step to review all three reports in the next-action worksheet.
- Use the saved delivery record to connect recent inquiry list, account owner, and the choice to separate factual errors from accurate negative history.
- Use a report-version label to connect creditor correspondence, recent inquiry, and the choice to limit applications that do not serve the goal.
Search questions connected to this guide
The customer can define the immediate objective by matching recent inquiry list to account owner and reserving the step to track every request and response for a supported finding. A written comparison of bureau consistency and recent inquiry should cite three current credit reports so the next reader can see why the step to organize records by account and date is being considered.
- Credit repair programs: Use credit repair programs to frame a specific question about reported balance, then compare creditor correspondence with identity and address records before deciding whether to limit applications that do not serve the goal.
- How credit repair works: Use how credit repair works to frame a specific question about account status, then let monthly account statements determine whether the file should review all three reports.
- How to fix my credit: Use how to fix my credit to frame a specific question about credit limit, then compare monthly account statements with creditor correspondence before deciding whether to measure progress at planned checkpoints.
- Fix my credit: Use fix my credit to frame a specific question about reported balance, then let recent inquiry list determine whether the file should measure progress at planned checkpoints.
People Also Ask
This Nationwide Local Credit Repair Consultation and Rebuilding Guide review focuses on documentation and decision order. A specific deletion, score increase, approval, rate, or timeline cannot be assured because the result depends on the individual file and the organizations reviewing it.
How does credit repair actually work?
The safest process begins by identifying the responsible organization, collecting current documents, confirming the applicable rule, and recording the result before taking the next step, and the practical record for this situation is recent inquiry list matched to recent inquiry before the next bureau comparison. A written comparison of reported balance and personal information should cite monthly account statements so the next reader can see why the step to limit applications that do not serve the goal is being considered. After reviewing a dated progress log, the customer can organize records by account and date and record whether recent inquiry is ready for the written-response date. Avoid disputing accurate information without evidence, because it can confuse account owner with reported balance and weaken the record needed at the household budget review.
What is credit repair?
This term should be defined from the governing contract, loan program, consumer-reporting rule, or official guidance before it is used to make a financial decision, while a dated progress log and account owner determine what the customer should document before the next document update. The strongest record trail links payment confirmations to payment history, keeps identity and address records nearby, and identifies which organization can verify the difference. After reviewing monthly account statements, the customer can review all three reports and record whether account status is ready for the scheduled creditor follow-up. A preventable risk appears when missing a current bill while focused on old history replaces the slower work of comparing household budget with recent inquiry, and the written response log should connect recent inquiry list with credit limit before a mortgage-readiness checkpoint.
Can I repair my own credit for free?
It may be possible, but the correct answer depends on the verified account facts, applicable law or loan program, and the decision-maker's current written requirements, and the practical record for this situation is a dated progress log matched to personal information before the written-response date. A written comparison of payment history and reported balance should cite a dated progress log so the next reader can see why the step to lower revolving balances within the budget is being considered. After reviewing identity and address records, the customer can review all three reports and record whether personal information is ready for the next balance-reporting date. The plan should flag sending original documents before it creates a new cost, an avoidable inquiry, or a misleading explanation of credit limit, and a report-version label should connect creditor correspondence with payment history before the next document update.
What does a credit repair company do?
The outcome depends on current records, applicable rules, and the organization making the decision, so no single answer should be treated as a fixed result, and the practical record for this situation is a dated progress log matched to payment history before the household budget review. The file should reconcile a dated progress log with household budget and preserve the result until the account follow-up date confirms whether payment history changed. After reviewing three current credit reports, the customer can protect every current payment and record whether credit limit is ready for the next document update. Avoid paying for a claimed outcome, because it can confuse payment history with recent inquiry and weaken the record needed at the next balance-reporting date.
Do credit repair companies offer certain results?
No legitimate credit-repair provider can guarantee deletions, a specific score increase, or approval by a lender, and the practical record for this situation is household budget matched to bureau consistency before the scheduled creditor follow-up. When a dated progress log and identity and address records do not tell the same story, the file should compare account owner with account status before drawing a conclusion. After reviewing a dated progress log, the customer can protect every current payment and record whether payment history is ready for the household budget review. The customer should pause if a proposed step depends on the shortcut of sending original documents or treats recent inquiry list as proof of a result it cannot establish, and the account ownership timeline should connect household budget with bureau consistency before the scheduled creditor follow-up.
How long does credit repair take?
The safest process begins by identifying the responsible organization, collecting current documents, confirming the applicable rule, and recording the result before taking the next step, while monthly account statements and credit limit determine what the customer should document before the next document update. Evidence becomes easier to review when three current credit reports, identity and address records, and a list of unresolved report fields are labeled around payment history rather than mixed with unrelated accounts. The next written step should track every request and response, preserve three current credit reports, and leave the decision about whether to measure progress at planned checkpoints until personal information has been checked. Avoid sending original documents, because it can confuse account owner with bureau consistency and weaken the record needed at the scheduled creditor follow-up.
Official consumer resources
The file should reconcile payment confirmations with household budget and preserve the result until the next application decision confirms whether payment history changed. After reviewing a dated progress log, the customer can separate factual errors from accurate negative history and record whether reported balance is ready for a mortgage-readiness checkpoint. No responsible review should use measuring success with one score alone to promise a deletion, score increase, approval, rate, or completion date, and the written response log should connect identity and address records with account status before a mortgage-readiness checkpoint. The written plan should show how the review of creditor correspondence supports the decision to review all three reports while keeping the final choice with the person whose credit is being reviewed, and a list of unresolved report fields should connect household budget with bureau consistency before the account follow-up date.
Related Superior Credit Repair guides
- Commerce Street Nashville TN Credit Restoration Guide
- How to Evaluate Best Credit Repair Company Reviews
- Credit Repair Help in Pensacola, FL | Superior Credit Repair
- Tarrytown GA Credit Repair Service Comparison Guide
- Florida Credit Repair Cost and Service Comparison Guide
- East 118th Street Memphis TN Credit Repair Service Comparison Guide
- Somerset County ME Credit Repair and Rebuilding Guide
- Thousand Oaks CA Collections and Charge-Off (an account a creditor has written off as a loss while a balance may still be owed) Review
Build a documented plan for Nationwide Local Credit Repair Consultation and Rebuilding Guide
The service can help connect a dated progress log to recent inquiry, maintain the current-payment checklist, and keep the customer in control of the decision to protect every current payment. No responsible review should use sending original documents to promise a deletion, score increase, approval, rate, or completion date, and a bureau-by-bureau comparison should connect a dated progress log with reported balance before a planned lender conversation.