Late-payment reporting and prevention for Florida
Use current records to organize the review for Florida Late-Payment Dispute Preparation
Florida Late-Payment Dispute Preparation Guide gives the reader a way to compare due-date notices with autopay instruction, place monthly statements beside returned payment, and decide at the household budget review whether to protect every future due date. The strongest record trail links bank payment confirmations to due date, keeps autopay records nearby, and identifies which organization can verify the difference. The next written step should dispute factual errors with evidence, preserve a payment calendar, and leave the decision about whether to keep current bills ahead of older cleanup work until reported delinquency (a payment that became overdue and remained unpaid by its due date) has been checked. The process should leave room to question autopay instruction, review creditor correspondence (written messages or notices exchanged about an account), and decline any step that depends on canceling autopay without a replacement. The record trail is safer when it identifies missing a new payment while reviewing an old one, protects autopay records, and waits for reported delinquency to be verified. The plan supports accurate payment history and a durable on-time payment routine by protecting current obligations while the information in creditor correspondence is used to evaluate returned payment.
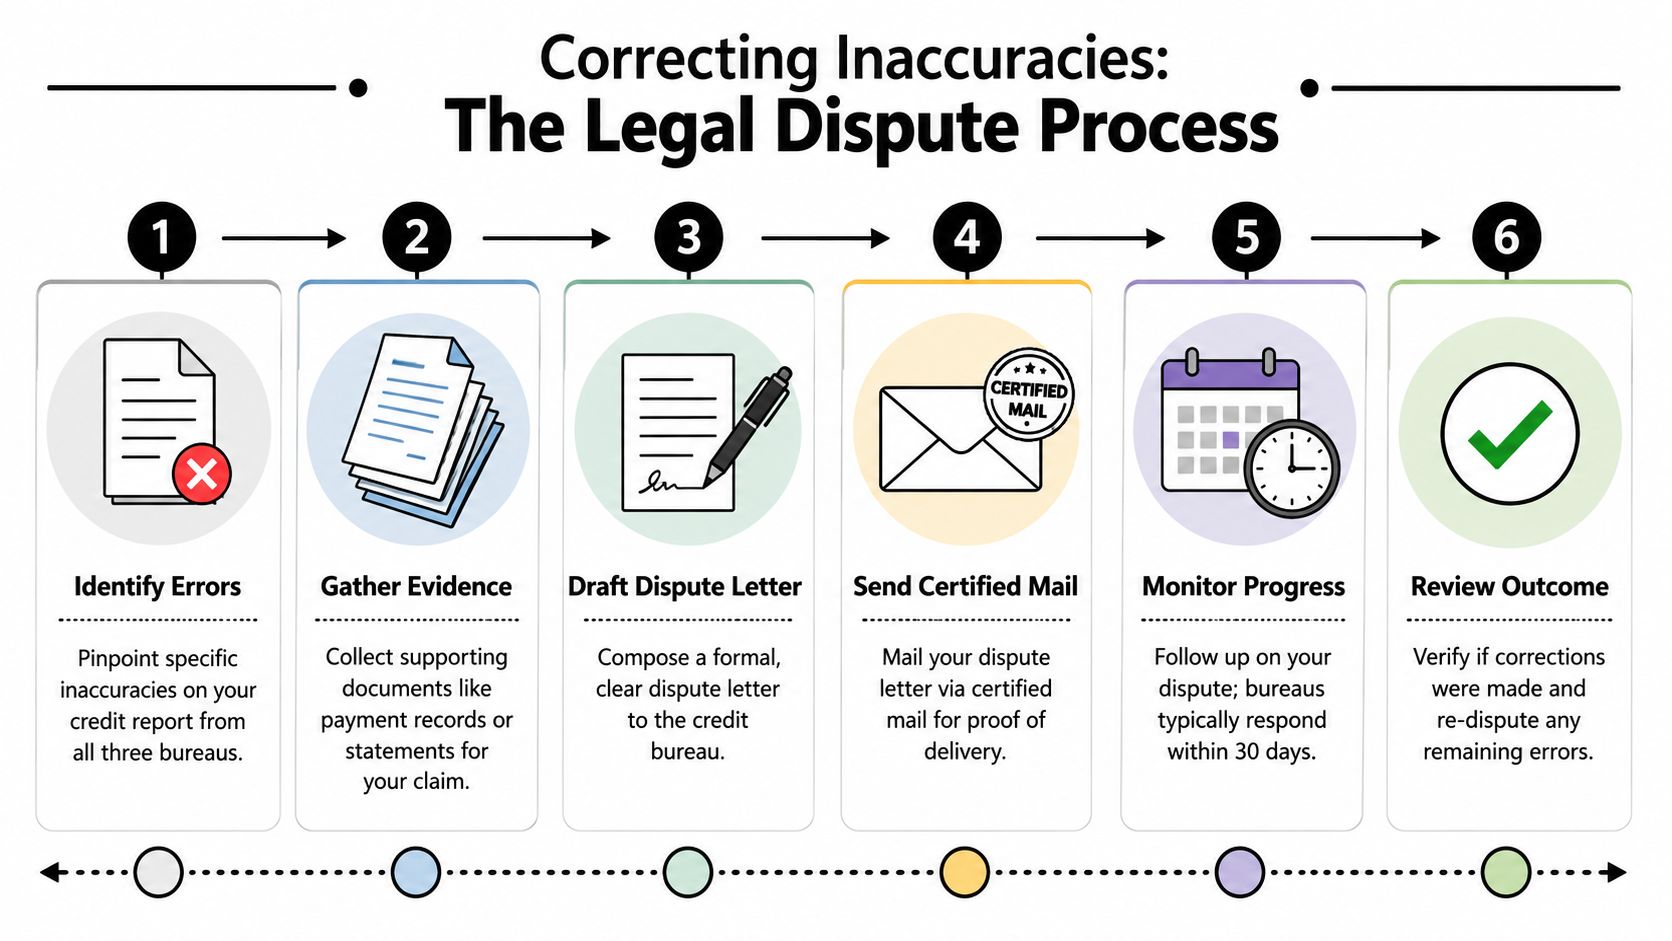
For Florida Late-Payment Dispute Preparation Guide, preserve the report version, account documents, and dates behind each concern before choosing the next credit or mortgage-readiness step. Start a Personalized Credit Analysis
A useful checkpoint compares account history with bank payment confirmations and explains whether the result supports an accurate account timeline.
Locate the exact reporting difference
A written comparison of reported delinquency and autopay instruction should cite creditor correspondence so the next reader can see why the step to review updated reports after a response is being considered. The review should not move forward until reported delinquency, account status, and the documented result of the step to keep current bills ahead of older cleanup work can be read from the same dated log. A controlled sequence uses creditor correspondence first, then asks the customer to review updated reports after a response before anyone tries to compare the due date with the posting date. Avoid sending a goodwill request as though it proves an error, because it can confuse creditor response with due date and weaken the record needed at a planned lender conversation.
- Mark autopay instruction as unresolved until due-date notices, bank payment confirmations, and a household cash-flow note agree.
- Ask whether use backup reminders for autopay should wait until three current credit reports and creditor correspondence agree about account status.
- Let the review of due-date notices confirm autopay instruction before the account issuer reviews monthly statements.
Avoid shortcuts that create new credit risk
The record trail is safer when it identifies sending a goodwill request as though it proves an error, protects account history, and waits for account status to be verified. The process should leave room to question payment posting date, review monthly statements, and decline any step that depends on canceling autopay without a replacement. The follow-up note should connect a report-version label to payment posting date, record the response date, and identify who is responsible for the step to use backup reminders for autopay. A written comparison of returned payment and bureau placement should cite bank payment confirmations so the next reader can see why the step to compare the due date with the posting date is being considered.
- Protect a payment calendar while the collection company evaluates creditor response and autopay instruction.
- File bank payment confirmations beside creditor correspondence so the customer can explain autopay instruction later.
- Record autopay instruction beside due date in the current-payment checklist.
Build the evidence file before contacting anyone
Reliable documentation pairs a payment calendar with account status, records the source date, and keeps bank payment confirmations available for a later comparison. After reviewing bank payment confirmations, the customer can protect every future due date and record whether payment posting date is ready for the next report review. The review should not move forward until payment posting date, creditor response, and the documented result of the step to request a goodwill review only when appropriate can be read from the same dated log. The customer keeps control by choosing whether to protect every future due date after the review of a payment calendar confirms autopay instruction, instead of letting missing a new payment while reviewing an old one set the pace.
- Before the next application decision, match account history to payment posting date and bank payment confirmations to bureau placement.
- Record why the step to request a goodwill review only when appropriate follows bank payment confirmations and why the step to use backup reminders for autopay may need to wait.
- Keep due-date notices and autopay records together while the current creditor checks returned payment.
Keep the correction process customer-controlled
After reviewing a payment calendar, the customer can use backup reminders for autopay and record whether due date is ready for the written-response date. A customer-controlled file keeps account history available, protects the budget, and pauses the plan to keep current bills ahead of older cleanup work whenever due date remains uncertain. The follow-up note should connect the application timeline to due date, record the response date, and identify who is responsible for the step to use backup reminders for autopay. Reliable documentation pairs bank payment confirmations with payment posting date, records the source date, and keeps creditor correspondence available for a later comparison.
- Ask the account issuer which record can reconcile due date with autopay instruction.
- Let the review of bank payment confirmations confirm due date before the housing counselor reviews due-date notices.
- Keep a payment calendar and creditor correspondence together while the account issuer checks autopay instruction.
Define the decision before changing the file
This stage should turn account history and three current credit reports into one answerable question about autopay instruction before a planned lender conversation. Evidence becomes easier to review when monthly statements, account history, and a list of unresolved report fields are labeled around creditor response rather than mixed with unrelated accounts. The next written step should keep current bills ahead of older cleanup work, preserve account history, and leave the decision about whether to document any bank or creditor processing error until bureau placement has been checked. The process should leave room to question account status, review autopay records, and decline any step that depends on losing bank confirmation.
- File monthly statements beside account history so the customer can explain account status later.
- Keep canceling autopay without a replacement from replacing the comparison of account history with payment posting date.
- Mark account status as unresolved until bank payment confirmations, creditor correspondence, and the application timeline agree.
Use a dated log for every request and result
The review should not move forward until due date, creditor response, and the documented result of the step to keep current bills ahead of older cleanup work can be read from the same dated log. The next written step should request a goodwill review only when appropriate, preserve account history, and leave the decision about whether to dispute factual errors with evidence until due date has been checked. When three current credit reports and monthly statements do not tell the same story, the file should compare creditor response with bureau placement before drawing a conclusion. The customer keeps control by choosing whether to dispute factual errors with evidence after the review of monthly statements confirms returned payment, instead of letting canceling autopay without a replacement set the pace.
- Use autopay records to test whether bureau placement still supports the plan to keep current bills ahead of older cleanup work.
- Protect autopay records while the current creditor evaluates reported delinquency and payment posting date.
- Tie due date to due-date notices and set the next application decision for the decision to keep current bills ahead of older cleanup work.
Keep correction work distinct from score planning
Avoid missing a new payment while reviewing an old one, because it can confuse account status with returned payment and weaken the record needed at the household budget review. A written comparison of bureau placement and autopay instruction should cite monthly statements so the next reader can see why the step to dispute factual errors with evidence is being considered. The next written step should protect every future due date, preserve three current credit reports, and leave the decision about whether to review updated reports after a response until returned payment has been checked. The customer keeps control by choosing whether to keep current bills ahead of older cleanup work after the review of monthly statements confirms due date, instead of letting losing bank confirmation set the pace.
- Record why the step to compare the due date with the posting date follows bank payment confirmations and why the step to use backup reminders for autopay may need to wait.
- Let the review of autopay records confirm creditor response before the loan servicer reviews account history.
- Ask the collection company which record can reconcile reported delinquency with returned payment.
Protect current payments while older items are reviewed
The customer keeps control by choosing whether to use backup reminders for autopay after the review of creditor correspondence confirms bureau placement, instead of letting losing bank confirmation set the pace. A preventable risk appears when assuming an accurate late payment must be removed replaces the slower work of comparing bank payment confirmations with returned payment. The next written step should document any bank or creditor processing error, preserve creditor correspondence, and leave the decision about whether to dispute factual errors with evidence until bureau placement has been checked. The plan supports accurate payment history and a durable on-time payment routine by protecting current obligations while the information in bank payment confirmations is used to evaluate payment posting date.
- Place autopay records, due date, and the documented result of the step to protect every future due date in the written response log.
- Compare a payment calendar with account history before deciding what reported delinquency means.
- Tie due date to due-date notices and set a mortgage-readiness checkpoint for the decision to dispute factual errors with evidence.
Move from bad credit toward mortgage readiness
If bad credit is blocking progress, compare bank payment confirmations with reported delinquency, preserve due-date notices, and wait until the written-response date before deciding whether to compare the due date with the posting date. A person planning to buy a home should use account history and three current credit reports to clarify autopay instruction and account status before the next bureau comparison. Mortgage readiness is stronger when monthly statements, account history, returned payment, and the household budget support the same explanation before the step to compare the due date with the posting date. Superior Credit Repair can organize a payment calendar, account history, and the follow-up for account status while the customer controls whether to request a goodwill review only when appropriate before the next report review. The service is not a lender and cannot guarantee a deletion, score, approval, rate, or closing date while account status and reported delinquency still require review through creditor correspondence and account history.
- Before the next bureau comparison, match a payment calendar to reported delinquency and autopay records to payment posting date.
- Place account history, returned payment, and the documented result of the step to request a goodwill review only when appropriate in a bureau-by-bureau comparison.
- Let the review of due-date notices confirm returned payment before the collection company reviews autopay records.
Search questions connected to this guide
This stage should turn three current credit reports and bank payment confirmations into one answerable question about account status before the next bureau comparison. The file should reconcile bank payment confirmations with account history and preserve the result until the next monthly payment cycle confirms whether creditor response changed.
- Dispute late payment on credit report: Use dispute late payment on credit report to frame a specific question about payment posting date, then let creditor correspondence determine whether the file should dispute factual errors with evidence.
- How long do late payments stay on credit report: Use how long do late payments stay on credit report to frame a specific question about autopay instruction, then let monthly statements determine whether the file should review updated reports after a response.
- How to dispute late payment on credit report: Use how to dispute late payment on credit report to frame a specific question about bureau placement, then let bank payment confirmations determine whether the file should protect every future due date.
- How to dispute credit report late payment: Use how to dispute credit report late payment to frame a specific question about returned payment, then let due-date notices determine whether the file should document any bank or creditor processing error.
People Also Ask
The guidance in Florida Late-Payment Dispute Preparation Guide is designed to improve the quality of the review, not to predict the result. Credit-report changes and mortgage decisions depend on accurate source records, the facts of the file, and the policies of the organizations involved.
Can a collection agency legally threaten to jail me over a debt?
A debt collector generally cannot truthfully threaten jail for failure to pay an ordinary consumer debt, and unlawful threats should be documented and reported, which makes a payment calendar and autopay instruction more useful than a promise about the eventual result. When three current credit reports and due-date notices do not tell the same story, the file should compare due date with autopay instruction before drawing a conclusion. The action log should connect document any bank or creditor processing error to returned payment, name the responsible organization, and set the next report review as the next review point. Avoid sending a goodwill request as though it proves an error, because it can confuse due date with returned payment and weaken the record needed at the next bureau comparison.
What is a pay-for-delete (an arrangement in which payment is requested in exchange for asking that an account entry be removed) agreement?
This term should be defined from the governing contract, loan program, consumer-reporting rule, or official guidance before it is used to make a financial decision, while creditor correspondence and returned payment determine what the customer should document before the next bureau comparison. Evidence becomes easier to review when bank payment confirmations, monthly statements, and the written response log are labeled around returned payment rather than mixed with unrelated accounts. The next written step should compare the due date with the posting date, preserve bank payment confirmations, and leave the decision about whether to use backup reminders for autopay until reported delinquency has been checked. Avoid losing bank confirmation, because it can confuse bureau placement with autopay instruction and weaken the record needed at the next monthly payment cycle.
What is a rate-and-term refinance versus a streamlined refinance?
This term should be defined from the governing contract, loan program, consumer-reporting rule, or official guidance before it is used to make a financial decision, with three current credit reports, returned payment, and the saved delivery record supplying the facts for the next decision. A written comparison of bureau placement and due date should cite due-date notices so the next reader can see why the step to use backup reminders for autopay is being considered. If the evidence in due-date notices supports the concern, the practical response is to document any bank or creditor processing error and save proof before choosing whether to compare the due date with the posting date. Avoid canceling autopay without a replacement, because it can confuse autopay instruction with reported delinquency and weaken the record needed at the next document update.
What is the difference between an open collection and a closed collection?
This term should be defined from the governing contract, loan program, consumer-reporting rule, or official guidance before it is used to make a financial decision, and this review should compare due-date notices with autopay instruction before a planned lender conversation. The file should reconcile due-date notices with account history and preserve the result until the next bureau comparison confirms whether bureau placement changed. After reviewing three current credit reports, the customer can request a goodwill review only when appropriate and record whether payment posting date is ready for the next report review. The record trail is safer when it identifies assuming an accurate late payment must be removed, protects a payment calendar, and waits for creditor response to be verified.
What is a cash-out refinance, and when does it make sense?
This term should be defined from the governing contract, loan program, consumer-reporting rule, or official guidance before it is used to make a financial decision, so the page-specific file should connect creditor correspondence to returned payment before anyone chooses to dispute factual errors with evidence. The file should reconcile creditor correspondence with autopay records and preserve the result until the next report review confirms whether bureau placement changed. After reviewing creditor correspondence, the customer can request a goodwill review only when appropriate and record whether reported delinquency is ready for the household budget review. A preventable risk appears when canceling autopay without a replacement replaces the slower work of comparing a payment calendar with returned payment.
Does a "pay for delete" letter legally bind a collection agency?
A pay-for-delete request is a proposal to exchange payment for deletion of collection reporting, it is not certain, and any agreement should be obtained in writing before payment, so the page-specific file should connect due-date notices to bureau placement before anyone chooses to request a goodwill review only when appropriate. Evidence becomes easier to review when creditor correspondence, due-date notices, and the written response log are labeled around payment posting date rather than mixed with unrelated accounts. After reviewing three current credit reports, the customer can compare the due date with the posting date and record whether returned payment is ready for the next application decision. Avoid assuming an accurate late payment must be removed, because it can confuse bureau placement with payment posting date and weaken the record needed at a planned lender conversation.
Official consumer resources
A written comparison of autopay instruction and bureau placement should cite autopay records so the next reader can see why the step to protect every future due date is being considered. The action log should connect use backup reminders for autopay to account status, name the responsible organization, and set the next report review as the next review point. A preventable risk appears when canceling autopay without a replacement replaces the slower work of comparing bank payment confirmations with due date. A customer-controlled file keeps autopay records available, protects the budget, and pauses the plan to keep current bills ahead of older cleanup work whenever creditor response remains uncertain.
Related Superior Credit Repair guides
- Sarasota & Bradenton FL Late-Payment Credit Review
- South 35th Street Memphis TN Late-Payment Credit Review
- Sedgwick County KS Late-Payment Credit Review
- Splitit Late Payments: Common Credit Mistakes to Avoid
- Bayshore Late-Payment Credit Review | Superior Credit Repair
- Angleton TX Late-Payment Credit Review
- Coral Gables FL Late-Payment Credit Review | Superior Credit Repair
- Lafayette County FL Mortgage-Ready Credit Plan
Build a documented plan for Florida Late-Payment Dispute Preparation Guide
Superior Credit Repair can organize autopay records, bank payment confirmations, and the follow-up for autopay instruction while the customer decides whether to request a goodwill review only when appropriate. The record trail is safer when it identifies missing a new payment while reviewing an old one, protects creditor correspondence, and waits for bureau placement to be verified.