General credit-repair planning nationwide
Check Credit limit in Payment confirmations before deciding whether to Separate factual errors from accurate negative history
Put payment confirmations beside recent inquiry list and find the dated value for account owner first. Use creditor correspondence (letters and other written messages), not an assumption about reported balance, to answer this checkpoint: What is inaccurate, incomplete, or unsupported? Do not stack several actions together. Record “Organize records by account and date” only after the record in monthly account statements supports that choice. Use creditor correspondence for the second comparison, this time on credit limit, so the file shows whether the problem is one field or two different issues. Stop if payment confirmations and three current credit reports still tell different stories about recent inquiry; the unresolved difference is the next item to investigate. The next review date for recent inquiry in monthly account statements should also resolve this question: Which current payment must be protected first? The closing note should identify the source for payment history and state whether “Limit applications that do not serve the goal” is still necessary.
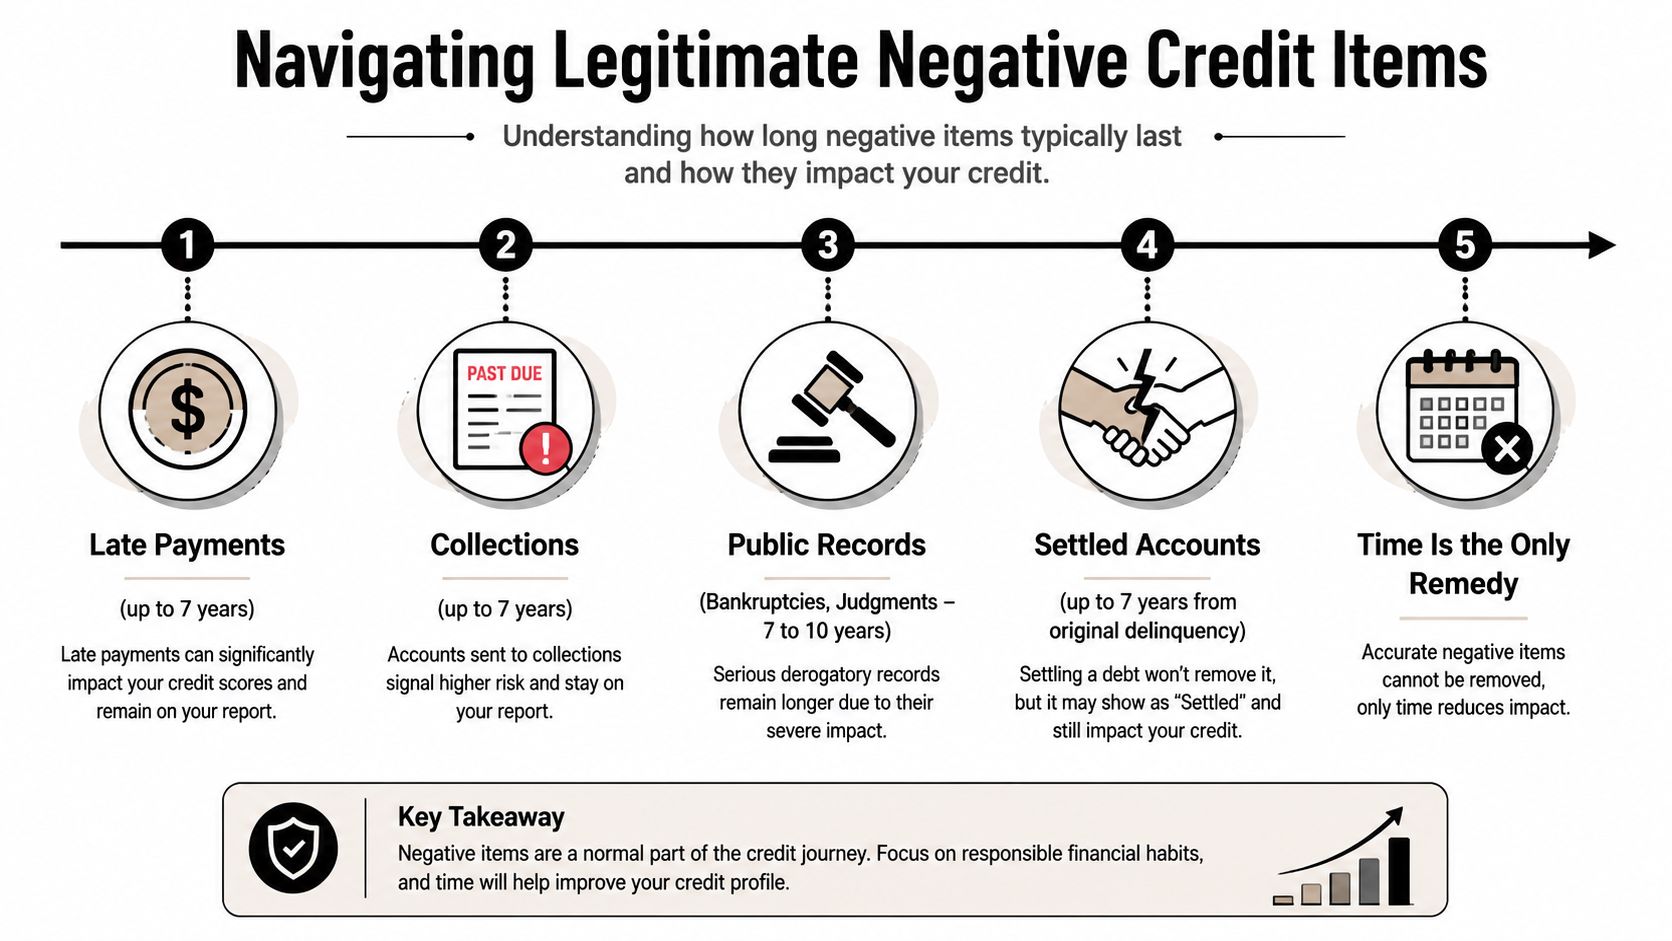
Review Account status in Payment confirmations before moving to the next documented step. For Credit limit, keep Recent inquiry list beside the response log, identify who owns the entry, and date the next comparison with Payment confirmations. With the nationwide Credit limit record open, the next step for Credit limit should come from Recent inquiry list and Payment confirmations, not from a promised score result or a fixed timeline. For the next decision about Credit limit, the customer can pause the Credit limit step when Recent inquiry list does not support it, or when timing, budget, or privacy concerns no longer fit the goal.
Start with the record that can verify Credit limit in Payment confirmations
In the review of Credit limit, after checking Identity and address records against Monthly account statements, the Credit limit review relies on Three current credit reports to tie Credit limit to Recent inquiry list, note the unresolved point, and define the evidence needed before moving on. With Identity and address records beside Reported balance, At the next Credit limit checkpoint, answer “What can be improved without adding new risk?” from Payment confirmations and record the source. A dated identity and address records record provides context for account owner; use a dated progress log as a separate check on payment history. After checking Account status in Creditor correspondence, close the Credit limit checkpoint only after Recent inquiry list shows what changed and the log identifies any remaining gap in Payment confirmations. For Credit limit, use Payment confirmations to support this step: tie Account status to Three current credit reports, note the unresolved point, and define the evidence needed before moving on.
- Is the Payment history difference between Monthly account statements and Creditor correspondence a reporting question or a separate rebuilding choice?
- Before another request is sent, what evidence in Three current credit reports would settle the Account status question for the Credit Repair for Auto Approval — Get Better Financing review?
- What source should support Reported balance before the file moves on to Account owner?
- Which date in Payment confirmations should trigger a fresh check of Credit limit against Recent inquiry list?
- Which change to Payment history should be recorded after comparing Payment confirmations with Three current credit reports?
Build the evidence trail for Credit limit with Payment confirmations
Keep Identity and address records available as evidence for Recent inquiry. For Reported balance, for Credit limit, connect each report question to a statement, notice, confirmation, or official record that can answer it using Payment confirmations. Compare Credit limit with Recent inquiry list before moving to the next documented step. In the nationwide file for Credit limit, connect each report question to a statement, notice, confirmation, or official record that can answer it. In the nationwide Account status review, confirm who is responsible for the Credit limit entry before another request leaves the file. Use the current evidence to decide whether to measure progress at planned checkpoints; only then consider whether to limit applications that do not serve the goal. Cross-check the entry in Identity and address records and Three current credit reports for Recent inquiry; avoid opening several new accounts; it can weaken the record trail or create a new problem while the original issue is still open.
- Creditor correspondence (letters and other written messages)
- Recent inquiry list
- Three current credit reports
- Payment confirmations
- Identity and address records
- Monthly account statements
Check whether Payment confirmations and Identity and address records agree on Credit limit
Using Creditor correspondence, review Account owner; keep Payment confirmations with the Credit limit review so the file can compare the same account, date, status, and balance across each bureau before deciding what is actually inconsistent. While checking Account status in Three current credit reports, the purpose is an accurate, stable credit file supported by realistic habits, not a fixed deletion, score increase, approval, rate, or completion date. Use creditor correspondence as the source for credit limit, then test that conclusion against payment confirmations. Before closing the checkpoint for Reported balance, use Identity and address records and Creditor correspondence to answer the Account owner question, then choose the next step from the documented difference. With Monthly account statements beside the Account owner entry, keep the account identifiers consistent between Recent inquiry list and Payment confirmations before treating the Credit limit difference as meaningful.
- Reported balance
- Recent inquiry
- Account owner
- Payment history
- Credit limit
- Account status
Keep the workflow tied to Credit limit and Payment confirmations
With Recent inquiry list beside the Credit limit entry, use the evidence in Recent inquiry list when the Credit limit review needs to move from review to evidence, action, response tracking, and a later checkpoint without repeating unsupported requests. Compare Payment history against Recent inquiry list, every recommendation should be tested with an accurate, stable credit file supported by realistic habits and the consumer's actual budget before the file moves on. For a nationwide review of Account owner using Creditor correspondence. For Credit limit, keep a completed correction separate from a pending request, denial, or rebuilding task documented in Payment confirmations. At the next Recent inquiry checkpoint, compare the saved record with Payment confirmations. For the nationwide Credit limit review, rely on Identity and address records and the consumer's own records rather than the page label. Start with track every request and response; after the file records that step with Identity and address records, lower revolving balances within the budget.
- Write the factual explanation for Credit limit
- Match Payment confirmations to the Credit limit finding
- Record delivery and response dates for Identity and address records
- Mark Account status on the saved report
- Send copies of Monthly account statements rather than original records
- Compare the response with the next report update for Reported balance
Use Credit limit to separate report accuracy from rebuilding
In the review of Account status, after checking Creditor correspondence against Three current credit reports, the next step for Credit limit is to treat a factual correction, debt decision, application decision, and rebuilding habit as different kinds of work. For Credit limit, use Payment confirmations to support this step: treat a factual correction, debt decision, application decision, and rebuilding habit as different kinds of work. With the nationwide Recent inquiry record open, a completed Credit limit review means the evidence and next action are recorded, not that an outside party must decide a certain way. Before closing Account owner, schedule one dated comparison with the current record. For Credit limit, apply the same evidence standard nationwide by checking Payment confirmations: use accurate documents, truthful explanations, and realistic expectations. Using Three current credit reports, review Reported balance; At the next Credit limit checkpoint, answer “What financial decision sets the timeline?” from Payment confirmations and record the source.
- When Identity and address records and Monthly account statements disagree, which dated entry should control the Account owner review?
- If Payment history changed after the last response, which entry in Creditor correspondence should be compared with Three current credit reports?
- Is the Account status difference between Payment confirmations and Creditor correspondence a reporting question or a separate rebuilding choice?
- Does Monthly account statements support the same Reported balance value shown in Payment confirmations, or does that difference need a separate note?
- Does Recent inquiry list support the same Recent inquiry value shown in Creditor correspondence, or does that difference need a separate note for the Credit Repair for Auto Approval — Get Better Financing review?
Request a Free Credit Analysis
Keep the record on Credit limit clear enough for independent review
Cross-check Identity and address records with Three current credit reports and save the result for Recent inquiry. For Recent inquiry, for Credit limit, rely on truthful records, focused explanations, and official guidance while avoiding claims that accurate information must be removed using Payment confirmations. For Credit limit, take this step first: protect every current payment. After the result is documented, review all three reports. With Recent inquiry list supporting the nationwide Payment history review, use Payment confirmations to test Credit limit against the current report before deciding whether another action is supported. Once Credit limit has a dated entry in Identity and address records, before closing Account status, use Three current credit reports to record what changed and Identity and address records to identify what still needs an answer. For Credit limit, use Payment confirmations to support this step: rely on truthful records, focused explanations, and official guidance while avoiding claims that accurate information must be removed.
- Which date in Payment confirmations should trigger a fresh check of Recent inquiry against Identity and address records for the Credit Repair for Auto Approval — Get Better Financing review?
- Before another request is sent, what evidence in Three current credit reports would settle the Account status question?
- What source should support Reported balance before the file moves on to Account owner?
- If Account status changed after the last response, which entry in Identity and address records should be compared with Three current credit reports?
- Which date in Monthly account statements should trigger a fresh check of Account status against Identity and address records?
Turn the search question into a check on Credit limit
With the entry in Three current credit reports and Three current credit reports compared for Payment history, With Payment confirmations as the evidence source, choose steps that support the stated objective without sacrificing current payments, essential expenses, or cash reserves. Keep Payment confirmations open while reviewing Reported balance. For Credit limit nationwide, check Payment confirmations against the current report and apply the relevant reporting rules; contracts, court deadlines, and local legal questions may require qualified local advice. For the nationwide Payment history check, use Payment confirmations to tie the Account status question to the evidence, protect current payments, and schedule a measured follow-up. For Account status in the supporting record, keep control of the Credit limit review by pausing before opening several new accounts and checking Payment confirmations. Review Identity and address records before choosing the next step on Credit limit; write the source beside the answer to “Which documents support the next step?” at the next Credit limit review.
- How credit repair works
- Credit repair programs
- How to fix my credit
- How do i fix my credit report myself
Use a dated log to follow Credit limit through each response
Using Creditor correspondence, review Account status; for Account owner, With Payment confirmations as the evidence source, record what changed, what stayed the same, what evidence was considered, and who owns the next follow-up. When reviewing Reported balance against Identity and address records, use Payment confirmations to track the first action: separate factual errors from accurate negative history. A later review can decide whether to track every request and response. For the nationwide Credit limit check, keep the Credit limit standard tied to an accurate, stable credit file supported by realistic habits and verify it in Payment confirmations instead of treating one score movement as proof. At the next documented review of Account status, the Reported balance checkpoint is ready to close when Payment confirmations documents the change, its source, and any question still open in Monthly account statements. Compare monthly account statements with creditor correspondence; the pair can show whether bureau consistency agrees with personal information.
- Record the date Payment confirmations were reviewed for Credit limit
- Write one factual note explaining the Account status difference
- Mark the Reported balance entry on a saved report
- Save copies of Identity and address records and keep the originals
- Match Monthly account statements to the account fact it supports
- Compare the response with the next report update for Credit limit
Watch for errors that can blur Credit limit in Payment confirmations
With Creditor correspondence beside the Payment history entry, the next documented step for Credit limit is to identify actions that can waste money, create inquiries, weaken documentation, or turn an accurate issue into a misleading claim. For Credit limit, use Payment confirmations to support this step: identify actions that can waste money, create inquiries, weaken documentation, or turn an accurate issue into a misleading claim. Use household budget as the source for payment history, then test that conclusion against identity and address records. After checking Credit limit in Identity and address records, record the answer to the Credit limit question beside Recent inquiry list: What is inaccurate, incomplete, or unsupported? In the review of Recent inquiry, after checking Identity and address records against Three current credit reports, for “credit repair programs”, start with one documented question about Credit limit and answer it from Payment confirmations.
- Combining Credit limit and Account status in one vague explanation
- Challenging a correct Reported balance entry only because it is negative
- Using an outdated Payment confirmations as the only evidence for Recent inquiry
- Discarding written responses tied to Account owner
- Sending a generic request without support from Identity and address records
- Assuming every bureau reports Credit limit the same way
Keep cash-flow decisions separate from Credit limit in Payment confirmations
In the review of Account owner, after checking Creditor correspondence against Monthly account statements, the next step for Credit limit is to keep new late payments and avoidable fees from undermining progress while correspondence or updates are pending. For Credit limit, use Payment confirmations to support this step: keep new late payments and avoidable fees from undermining progress while correspondence or updates are pending. Using Three current credit reports for the nationwide Credit limit check, for Credit limit, paying before the service terms and cancellation rights are clear is a reason to pause and verify the record. Use a dated progress log beside identity and address records to verify personal information before treating credit limit as related. Compare the entry in Payment confirmations with the saved Reported balance value; keep “how to fix my credit” tied to one checkable Credit limit question in Payment confirmations.
- Which date in Payment confirmations should trigger a fresh check of Recent inquiry against Identity and address records?
- Does Recent inquiry list support the same Credit limit value shown in Payment confirmations, or does that difference need a separate note for the Credit Repair for Auto Approval — Get Better Financing review?
- What source should support Reported balance before the file moves on to Account owner?
- Which date in Payment confirmations should trigger a fresh check of Credit limit against Recent inquiry list?
- Does Recent inquiry list support the same Recent inquiry value shown in Creditor correspondence, or does that difference need a separate note?
Questions to resolve about Account status with Payment confirmations
Use the questions below to clarify Account status for Credit Repair for Auto Approval — Get Better Financing Offers. For Credit Repair for Auto Approval — Get Better Financing Offers, answer each question with current records and realistic expectations.
- How do i fix my credit report myself — use Payment confirmations to check Credit limit before deciding what the search means for this file.
- Credit repair programs — use Identity and address records to check Account status before deciding what the search means for this file.
- How credit repair works — start with the Reported balance entry in Monthly account statements and compare it with Creditor correspondence before choosing a response.
- How to fix my credit — start with the Recent inquiry entry in Creditor correspondence and compare it with Recent inquiry list before choosing a response.
People Also Ask
What is inaccurate, incomplete, or unsupported?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with payment confirmations and a dated progress log so the answer is tied to current records. For this question about Credit limit, check account owner and recent inquiry separately, because one correct field does not prove that the full account entry is accurate. In the nationwide file for Reported balance, the practical next step is to lower revolving balances within the budget, record the result, and then decide whether it is appropriate to review all three reports. For the next decision about Account status, for consumers nationwide, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. In the review of Credit limit, after checking Identity and address records against Monthly account statements, no answer to “What is inaccurate, incomplete, or unsupported?” can honestly promise a deletion, score increase, approval, rate, or completion date.
What can be improved without adding new risk?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with payment confirmations and recent inquiry list so the answer is tied to current records. For this nationwide review of Recent inquiry, check payment history and account status separately, because one correct field does not prove that the full account entry is accurate. After checking Reported balance in Three current credit reports, the practical next step is to protect every current payment, record the result, and then decide whether it is appropriate to review all three reports. In the review of Account status, after checking Creditor correspondence against Three current credit reports, for consumers nationwide, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. When the question turns to Account status, no answer to “What can be improved without adding new risk?” can honestly promise a deletion, score increase, approval, rate, or completion date.
What financial decision sets the timeline?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with identity and address records and monthly account statements so the answer is tied to current records. For the next decision about Recent inquiry, check credit limit and payment history separately, because one correct field does not prove that the full account entry is accurate. For the Reported balance question on this page, using Three current credit reports as the source record, the practical next step is to lower revolving balances within the budget, record the result, and then decide whether it is appropriate to separate factual errors from accurate negative history. For a reader checking Reported balance against Three current credit reports, for consumers nationwide, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. For the nationwide Recent inquiry using Payment confirmations check, no answer to “What financial decision sets the timeline?” can honestly promise a deletion, score increase, approval, rate, or completion date.
How will responses be tracked?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with three current credit reports and monthly account statements so the answer is tied to current records. Applied to Recent inquiry in this file, with Identity and address records tied to the same account, check credit limit and personal information separately, because one correct field does not prove that the full account entry is accurate. For this question about Recent inquiry, the practical next step is to limit applications that do not serve the goal, record the result, and then decide whether it is appropriate to lower revolving balances within the budget. For this nationwide review of Payment history, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. At the next dated review of Account owner, no answer to “How will responses be tracked?” can honestly promise a deletion, score increase, approval, rate, or completion date.
Which documents support the next step?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with identity and address records and a dated progress log so the answer is tied to current records. For this question about Account owner, check reported balance and payment history separately, because one correct field does not prove that the full account entry is accurate. When reviewing Recent inquiry using Payment confirmations nationwide, the practical next step is to limit applications that do not serve the goal, record the result, and then decide whether it is appropriate to organize records by account and date. For the next decision about Payment history, for consumers nationwide, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. After comparing the Account owner entry in Creditor correspondence with Monthly account statements, no answer to “Which documents support the next step?” can honestly promise a deletion, score increase, approval, rate, or completion date.
Which current payment must be protected first?
For Credit Repair for Auto Approval — Get Better Financing Offers, begin with a dated progress log and household budget so the answer is tied to current records. In this nationwide Account status worksheet, check account owner and reported balance separately, because one correct field does not prove that the full account entry is accurate. After checking Credit limit in Identity and address records, the practical next step is to measure progress at planned checkpoints, record the result, and then decide whether it is appropriate to organize records by account and date. Once Reported balance has a dated entry in Three current credit reports, for consumers nationwide, legal deadlines or contract questions should be confirmed with the responsible organization or a qualified local professional. In the answer about Payment history, no answer to “Which current payment must be protected first?” can honestly promise a deletion, score increase, approval, rate, or completion date.
Official consumer resources
Official sources give Credit Repair for Auto Approval — Get Better Financing Offers a reliable starting point, but they do not decide the facts of a particular account. During the Credit limit review, use the first resource to understand the rules or consumer process connected to credit-repair planning review. While checking Credit limit in Payment confirmations, use the second to obtain or interpret the report information needed for the review. Document when the resource was accessed and which page was used, since reporting guidance can be updated. For Credit Repair for Auto Approval — Get Better Financing Offers, when the issue involves a lawsuit, bankruptcy choice, tax question, contract, or state deadline, seek advice from a qualified professional rather than treating this educational page as legal advice. For this file, charge-off (a debt the creditor wrote off as unpaid) should be documented separately from payment history before another action.
Related Superior Credit Repair guides
- Des Moines IA Credit Repair and Rebuilding Guide
- Superior Credit Repair Locations and Service Area Guide
- Chase Closed My Account: Steps Before Applying Again
- Tunica MS Post-Bankruptcy Credit Rebuilding Guide
- San Francisco CA 44 Montgomery Street Credit Service Comparison
- Sanibel FL Collections and Charge-Off Review
- Florida Credit Repair Reviews: Service Quality Checklist
- Wyandotte County KS Apartment Approval Credit Preparation
Build a documented plan for Credit Repair for Auto Approval — Get Better Financing Offers
Superior Credit Repair can help organize the reports, supporting records, response log, and rebuilding priorities for Credit Repair for Auto Approval — Get Better Financing Offers. With Monthly account statements open for Account owner, for Credit limit, use Payment confirmations to organize current reports, supporting records, budget priorities, and the next financial goal into a clear customer-controlled plan. Before the next nationwide Recent inquiry step, it does not promise deletions, score increases, approvals, rates, or completion dates, and the customer keeps control of every decision.